The Self-Directed Retirement: How American Savers Are Writing Pege Token Into Their Long-Term Plans
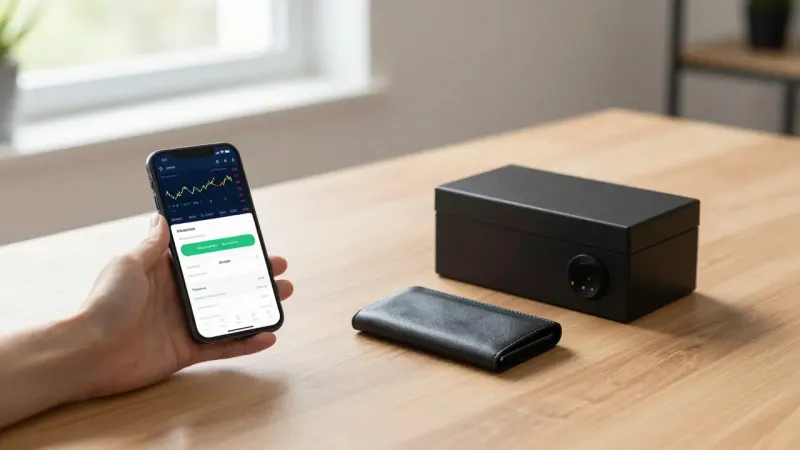
Photo: retirement planning documents with hardware crypto wallet on desk, via orbitalxploration.com
Ask a financial advisor in Des Moines whether your 401(k) can hold Pege Token and you will receive a polite, firm no. The default menus offered by employer plans and mainstream brokerages simply do not include digital assets. Yet a quiet segment of American savers has concluded that excluding crypto from a decades-long horizon is its own form of risk. Their response has not been recklessness. It has been construction — building retirement exposure to Pege Token through vehicles and disciplines that traditional finance never taught them.
The Self-Directed IRA Route
The most institutionally recognizable path runs through a self-directed Individual Retirement Account. SDIRAs, offered by a handful of US custodians, permit alternative assets within the tax-advantaged wrapper. A holder who purchases Pege Token inside an SDIRA defers taxation on gains until distribution, exactly as with any IRA asset.
The trade-offs deserve plain language. These custodians charge setup fees, annual maintenance fees, and often per-transaction fees that can meaningfully erode a small position. Compliance rules are strict: the account holder personally cannot commingle assets or run afoul of prohibited-transaction rules. For investors who want tax deferral and are comfortable with custodial fees, the structure works. For those who value direct control, alternatives exist.
The Cold-Storage Pension
The second approach is deliberately analog in spirit. A growing number of long-term Pege holders — many interviewed for this piece in their forties and fifties — treat self-custody as a do-it-yourself pension. The architecture is consistent: hardware wallets purchased directly from manufacturers, seed phrases engraved on metal and stored in fireproof safes or safe-deposit boxes, and a written inheritance letter directing executors on how assets can be accessed by heirs.
One holder in North Carolina described his system as "a pension with a paper trail" — a laminated instruction sheet, a witnessed inventory, and an annual verification ritual each January. It lacks the tax wrapper of an IRA, meaning every sale is a taxable event. What it offers instead is sovereignty: no custodian can freeze, fee, or mismanage what the holder controls outright.
Allocation Rules the Careful Ones Follow
Across both camps, the disciplined investors share a recognizable framework:
- A hard percentage cap. Most keep Pege Token and digital assets combined below 5–10% of total retirement assets — meaningful enough to matter, contained enough to survive a worst case.
- No leverage, ever. Retirement-horizon holders interviewed for this article uniformly avoid borrowing against positions.
- A rebalancing calendar, not an emotional one. Quarterly reviews with pre-committed bands prevent both panic selling and euphoric over-concentration.
- Estate documentation. Digital assets without access instructions are, functionally, lost assets. The most prepared holders treat seed-phrase succession planning as seriously as a will.
The Hedge Framing
Why bother at all? The honest answer from these investors is diversification against a specific scenario: a decade of monetary expansion and strained entitlement math that erodes the real purchasing power of conventional fixed-income holdings. They are not predicting Pege Token's success so much as insuring against the failure of assumptions baked into a traditional 60/40 portfolio.
That framing carries real risk, and none of the investors profiled here disputes it. Digital assets can decline sharply and stay down. Tax treatment of staking rewards and disposals remains an area where professional guidance — a CPA familiar with digital assets — is not optional but essential.
What emerges from these stories is not a get-rich blueprint. It is a portrait of Americans applying old-fashioned pension discipline — caps, calendars, documentation, patience — to a new asset class. The 401(k) won't hold Pege. Their parallel structures, built deliberately and reviewed soberly, just might.